Showing posts with label Singtel. Show all posts

Tuesday, 1 August 2017

GoHuat’s Views on Current STI Market and Upcoming Plans


Over the past few months, the STI has risen steadily to the current support level of 3300-3350. One potential thought is to sell off some shares in CPF Investment Account to preserve some of its gains. Based on current market conditions, my target sell prices for the shares in my CPFIA are as follows: OCBC@S$11.50; for STI ETF@S$3.52; and for Singtel@S$4.25. My CPFIA portfolio is expected to achieve an estimated returns of around 2.56% in 2017, based on total dividends over total purchase price. (Note: My first purchase was in end Mar 2017 so I missed out some dividends before that).
I am also planning to start selling my cash investment once STI hits 3.5K or if there is a change in the global outlook. Over the past few months, I have accumulated more Singtel shares. My current portfolio consisted of 3 “anchor” shares - Singtel, MapleTree Logistics Trust (MLT) and Ascendas Hospitality Trust (AHT). These 3 shares formed around 25% of my portfolio in terms of purchase value. The remaining 75% are shared between Finance (i.e. Banks and financial companies) and Oil & Gas shares.
My "anchor" shares have performed well while paper losses in O&G shares remained a sore thumb. However, I am happy that the damage has been reduced by my timely shift into “anchor” shares. My current view is that the O&G sector is starting to show some minor recovery signs, with indicators such as the rise in oil prices and early interest to buy over completed Sembcorp Marine’s rigs. Related to this is a recent report published by DBS on the potential merging of Keppel and Sembcorp Marine. I thought it would be interesting to share my facebook views here:

Will both companies merge? Though there are benefits of cutting cost during this downturn, I still think that the sector has a good chance of recovering  in the longer term. I also agree with this article that a merger will cause a monopoly issue in Singapore. Hence, my current belief is that the likelihood of a merger is low. What are your views on this?
Together, let us all Go & Huat ah!
GoHuat

Related Posts
Why should we ever use our CPFOA for Investment?

Friday, 7 April 2017

5 Key Reasons for buying Singtel now


Over the past few months, share prices for my shortlisted REITs/TRUSTs have been rallying beyond my target buy price. And so, I decided to explore whether there are other potential shares that could also fit well into my overall investment strategy. After going through a long process of analysing several potential companies such as ST Engineering, Sheng Shiong, SGX, etc, I was rather glad to find Singtel to be a suitable fit and thought that it will be useful to share my 5 key reasons here.

Reason 1: Singtel’s Earnings & Net Asset per share have been on a steady up-trend over the last few years. While there are risks of increasing competition from the 4th telco (TPG) or companies with other disruptive technologies, my view is that these should not affected Singtel’s earnings much in the foreseeable future as the competitors will likely not be mature enough.

Source: Singtel


Reason 2: Singtel has sound & stable business fundamentals with high dividend payout at 60-75% of their Net Profit. Its current dividend yield is around 4.5% which is relatively high.

Source: Singtel

Reason 3: A key business risk - foreign exchange rate - has been relatively well-managed.

Reason 4: Looking ahead, I found Singtel’s investment in the 5G network to have a lot of business potential, especially with Singapore’s push to become a Smart Nation. The 5G network infrastructure should become an essential backbone in enabling faster and smarter connections - Internet of Things. All these would likely give Singtel a greater competitive edge over their rivals in the future.

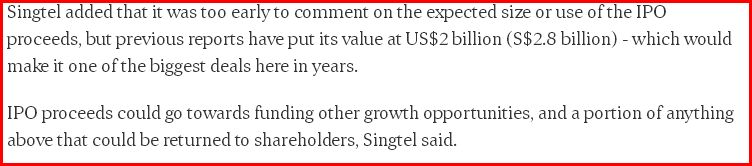
Reason 5: Singtel is preparing their fibre broadband unit NetLink Trust for an IPO before Apr 2018; which should translate to a much higher share price in near-term or higher dividend pay-out. See extracts from Straits Times below: 


 Source: Straits Times

So what have I done?

Using both cash and CPF OA, I have made several rounds of purchase last month. Currently, Singtel forms around 7.5% of my cash portfolio and I am likely to buy more share in the next few weeks. 

Will the outcome be as what I have assessed above? I certainly hope so, but we will never know until it truly happens! 

Together, let us all Go & Huat ah!
GoHuat